Roof insurance claims in Oklahoma
Understand the difference between the roofing work and the policy payment, including depreciation, deductibles and roof-specific insurance terms.
The roof work and the insurance payment are different questions
A damaged roof creates two related tasks: deciding what the building needs and finding out what the insurance policy covers. The first follows the roof’s condition. The second depends on the cause of loss, policy terms and the insurer’s decision. Keeping those tasks clear helps explain why a roofing proposal and a claim payment may differ.
This guide gives Oklahoma homeowners the main terms in ordinary language. A free roof inspection can help explain visible conditions while the insurer answers the coverage questions.
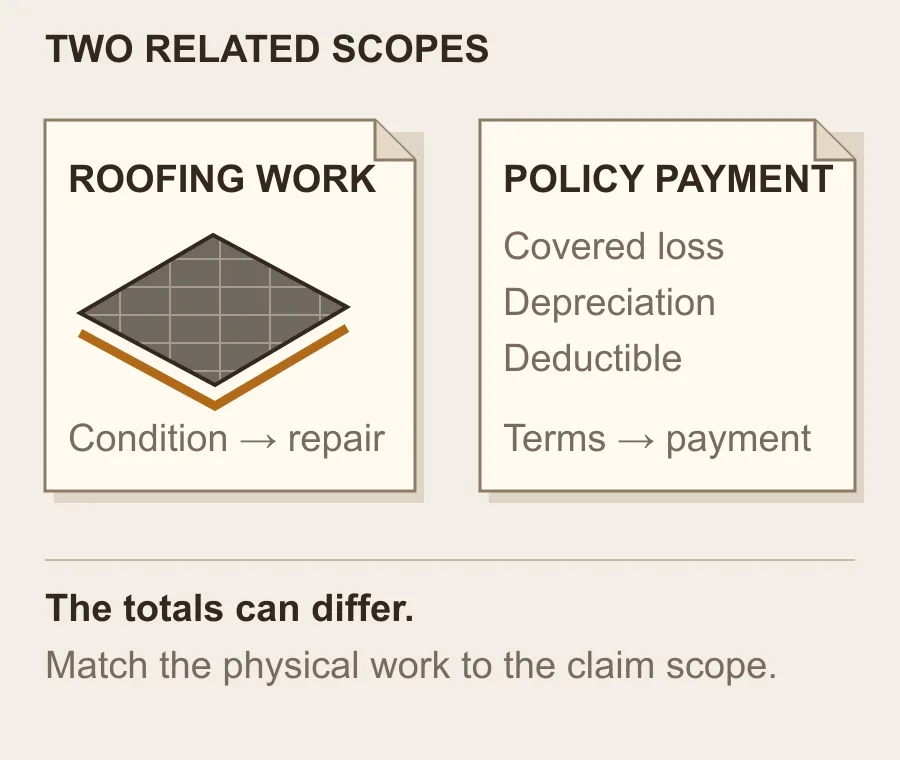
- Roofing proposal
- The roof’s condition and the physical repair or replacement work.
- Claim payment
- The covered loss, policy terms, depreciation and deductible. This amount can differ from the roofing proposal.
Understand ACV and replacement-cost coverage
The Oklahoma Insurance Department’s post-disaster claims guide explains the importance of policy terms, depreciation and claim documentation. The examples here describe the concepts; your policy and insurer determine how they apply.
From roof condition to a claim decision
- Start with safety and the actual condition
Keep away from damaged roof areas, sagging ceilings and wet electrical fixtures. Existing photos, the date you noticed a change and safe ground-level observations can help describe the concern without climbing onto the roof.
- Explain what the roof inspection finds
A roofer can identify visible damage and the work needed to reconnect the roof. Concealed layers may require further investigation. Findings about the roof do not by themselves decide the policy cause of loss or payment.
- Report through the insurer’s process
Reporting requirements and deadlines depend on the policy and the situation. The insurer can explain its claim process and what information it needs. Preserve relevant records and receipts for reasonable protective work rather than assuming they will all be reimbursed.
- Compare the scopes before work proceeds
The roofing scope should identify the physical work, and the claim documents should show what the insurer has allowed. Differences can include measurements, concealed damage, policy limits or a chosen upgrade. Clarifying the difference is more useful than assuming every gap has the same cause.
Oklahoma roof insurance FAQs
Does insurance cover a roof that is simply wearing out?
Ordinary wear is different from a covered event. The policy’s terms and the insurer’s determination control coverage. A roof can need replacement without that replacement being an insured loss.
Does a free inspection guarantee claim approval?
No. It can help explain the roof’s current condition and the work being considered. The insurer evaluates the claim under the policy; neither a weather report nor an inspection guarantees payment.
How soon do I have to report roof damage?
Check the policy’s notice requirements and contact the insurer promptly when considering a claim. Different policies and circumstances can have different deadlines, so a general website cannot establish the date for your claim.
Will replacement-cost coverage pay every dollar of a new roof?
Not necessarily. Deductibles, limits, exclusions, conditions for depreciation recovery and chosen upgrades can leave an owner share. The written policy and claim decision need to be read together.
Can I discuss roof work before I know whether insurance will pay?
Yes. The condition and repair options can be examined separately from the payment decision. Our storm damage service explains the physical work after weather.
Start by understanding the roof’s condition.
Tell us the property location and what brought you here. Start with a free roof inspection and a conversation about the work.